It’s the first question I get on almost every window estimate in Boca Raton, and I understand why. Your premium went up again, your neighbor says his went down after he did his windows, and you want to know if there’s real money on the other side of this job — or just a sales pitch.
There’s real money. But it doesn’t show up automatically, and it doesn’t show up the way most window salesmen describe it. Here’s how the credit actually works, and what has to be true before your carrier pays you a dime of it.
Key takeaways
- Yes — impact windows can lower a Florida homeowners premium, through the wind-mitigation credits your carrier applies after a wind mitigation inspection.
- The credit is about opening protection: in most cases every glazed opening — windows, doors with glass, the garage door, skylights — has to be protected, not just the front windows.
- The windows alone don’t pay you. A wind mitigation inspection on the state’s form, plus your permit, final inspection, and product approvals, is the paperwork that turns new windows into a lower premium.
- Savings vary by carrier, policy, and home — up to $1,400/year is the top end I quote, never a promise. A house with an older roof can still score poorly no matter how good the windows are.
- Done right, the math stacks: insurance savings, programs like My Safe Florida Home that have offered up to $10,000, and financing with approved credit can work together on the same job.
The short answer: yes — through wind mitigation
Florida carriers don’t give you a discount because your new windows look nice. They give it because protected openings make your house harder to blow apart in a storm. When wind gets inside through a failed window, pressure builds and the roof is what pays for it. Impact glass that stays in the frame keeps the envelope sealed — and that lower risk is what the credit prices.
Those credits live on a wind mitigation inspection — the state form (OIR-B1-1802) a licensed inspector fills out after walking your house. Opening protection is one section of that form. Your roof’s age and shape are other sections. I tell homeowners this straight: windows move one part of your score. They don’t rewrite the whole report, and anyone who quotes you a guaranteed premium number before that inspection exists is guessing with your money.
The catch: every opening counts
This is where partial jobs disappoint people. Do the front of the house this year and the back next year, and on paper your home still has unprotected openings — so the opening-protection credit is reduced or gone entirely until the job is complete. The same goes for the glazed door you skipped and the garage door nobody mentioned.
That’s not me upselling you more glass. It’s how the form is scored. When I measure a house, I count every opening first, and then we talk honestly about whether doing it in phases still makes sense for your budget — sometimes it does — with your eyes open about when the insurance piece kicks in.
The windows themselves also have to be the real thing: Florida Product Approval or a Miami-Dade Notice of Acceptance, installed to the approval, permitted, and final-inspected. Paper matters as much as glass here, which is why we pull the permit on every install. You can see how we handle it on our impact windows page, and start at onelconstruction.com to judge us on the work itself.
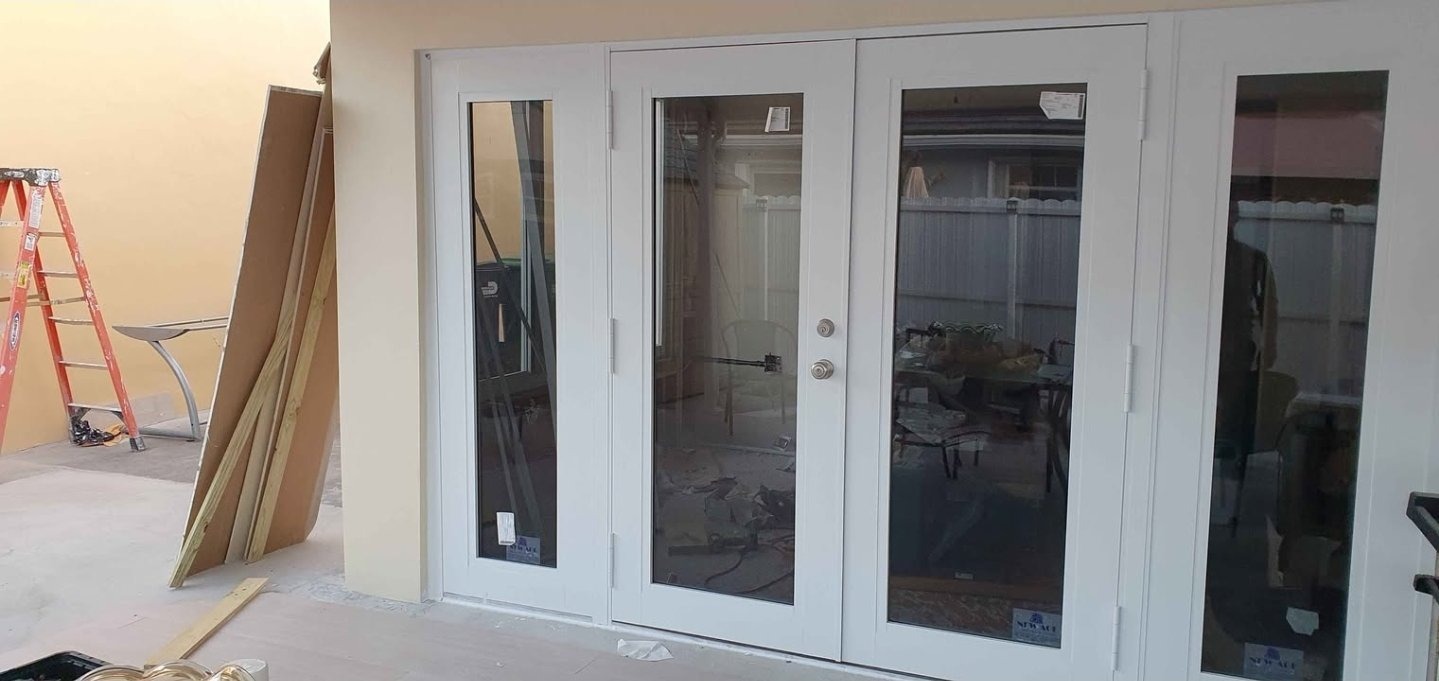
The paperwork that actually gets you the credit
New windows in the wall change nothing at your carrier until three things happen. First, the job passes its final inspection and the permit closes. Second, you get a fresh wind mitigation inspection that documents the new opening protection — keep your product approvals and install paperwork, because the inspector and the carrier may both want them. Third, that report goes to your agent or carrier, and the credit applies at renewal or by endorsement, depending on the company.
Do that sequence and the savings are real — up to $1,400/year on the homes where everything lines up.* Some houses see less. If your roof is near the end of its life, your report can still score poorly in the roof sections, and I’ll tell you that before you spend window money expecting it to fix a roof problem. How long the windows themselves will keep earning that credit is its own question — I covered realistic lifespans in how long impact windows last.
What the job costs, and how the math stacks
Real numbers, because that’s the only way this decision works. Impact windows start at $1,800 per window installed — that’s the floor, including delivery, removal of the old window, and installation — and go up with size, style, and glass options. From signing to installed currently runs about 6–8 weeks, most of it manufacturing and permitting, not crew time.*
Against that cost, stack what comes back: the insurance credit above, year after year. Programs like My Safe Florida Home have offered up to $10,000 toward hardening work like this — funding and eligibility are set by the program and change, and we help eligible homeowners navigate the application. And most homeowners finance the balance: small jobs from $120/month, typical projects in the low $200s–$300s/month, with approved credit, at rates as low as 4.49% APR with approved credit through our financing partner. No single piece has to carry the whole job — that’s what makes the math honest instead of hopeful.*
Ready to find out what your house would actually score?
Call or text me at (561) 462-9293 (call/text), or reach us through our contact page. I’ll come out, count every opening for free, tell you straight whether the full-protection credit is within reach for your house, and price the job with current numbers. If a phase plan makes more sense for your budget, I’ll say that too — and tell you exactly when the insurance piece starts.
Onel Construction LLC — a licensed Florida general contracting firm (CGC1511492). Licensed and insured, serving Boca Raton and a 75-mile radius — West Palm Beach to Miami.
Prices are averages from recent jobs, set before the latest round of tariff-driven material price increases, and subject to change with inflation, tariffs, and market conditions. Your free estimate always uses current numbers.
FAQ
Do I need impact glass on every window to get the insurance credit?
In most cases, yes — the opening-protection section of the wind mitigation form looks at all glazed openings: windows, doors with glass, skylights, and the garage door. Leave openings unprotected and the credit for that section is reduced or lost until the job is complete. That’s the main reason I count every opening before I quote anything.
How much will I actually save on my premium?
It varies by carrier, policy, and the rest of your wind mitigation report — roof age and shape count too. Up to $1,400/year is the top end on homes where everything lines up; plenty of homes see less. Nobody can honestly give you your number before a wind mitigation inspection documents your house. Anyone who guarantees it is selling, not measuring.
When does the lower premium start?
After the permit closes and a wind mitigation inspection documenting the new opening protection reaches your carrier. Depending on the company, the credit applies by endorsement mid-policy or at renewal. Keep your permit paperwork and product approvals — the inspector and the carrier may both ask for them.
Will impact windows fix my premium if my roof is old?
Not by themselves. Windows improve the opening-protection section of your report; an older roof still scores the way it scores in its own sections. I’ll tell you which problem is actually driving your premium before you spend on the wrong one — sometimes the roof has to come first.
Insurance savings vary by carrier, policy, and home — figures shown are ‘up to’ amounts, not guarantees. Grant eligibility, amounts, and funding availability are determined by the program and may change. Financing subject to lender approval; rates and payments vary by credit profile. All financing examples assume approved credit through our financing partner.